Feeds:
Posts
Comments

Above the Crowd

By Bill Gurley

The Dangerous Seduction of the Lifetime Value (LTV) Formula

September 4, 2012: Many consumer Internet business executives are loyalists of the Lifetime Value model, often referred to as the LTV model or formula. Lifetime value is the net present value of the profit stream of a customer. This concept, which appears on the surface to be quite benign, is typically used to compare the costs of acquiring a customer (often referred to as SAC, which stands for Subscriber Acquisition Costs) with the discounted positive cash flows that will come from that customer over time. As long as the sum of the discounted future cash flows are significantly higher than the SAC, then people will argue it is warranted to “push the accelerator,” which typically means burning capital by aggressively spending on marketing.

This is a simplified version of the formula:
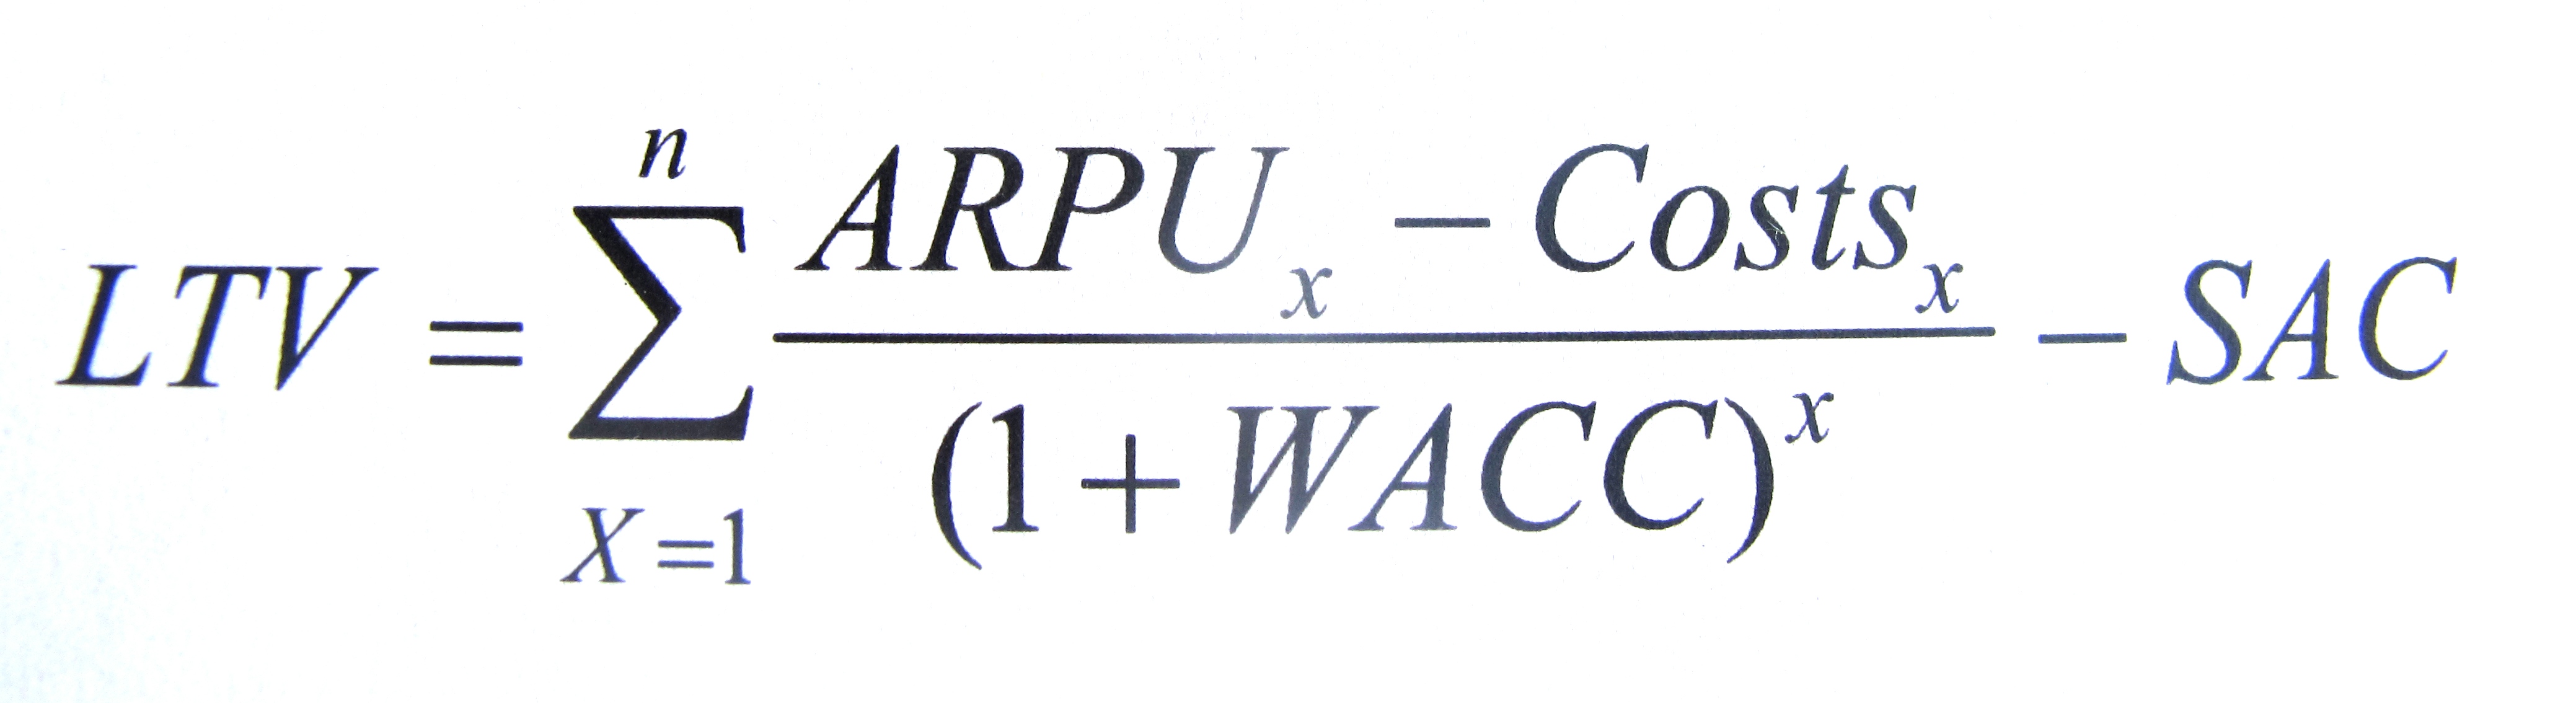
Image

The key statistics are as follows:

  • ARPU (average revenue per user)
  • Avg. Cust. Lifetime, n (This is the inverse of the churn, n=1/[annual churn])
  • WACC (weighted average cost of capital)
  • Costs (annual costs to support the user in a given period)
  • SAC (subscriber acquisition costs, sometimes refereed to as CAC = customer acquisition costs)

The LTV formula, when used correctly, can be a good tactical tool for monitoring and comparing like-minded variable market programs, especially across channels. But like any model, its proper use is entirely dependent on the assumptions used in that model. Also, people who have a hidden agenda or who confuse a model with reality can misuse it. For many companies that subscribe to its wisdom, the formula slowly takes on more importance than it should. Seduced by the model, its practitioners often lose sight of the more important elements of corporate strategy, and become narrowly fixated on the dogmatic execution of the formula. In these cases, the formula can be confused, misused, and abused, much to the detriment of the business, and in many cases the customer as well.

Here are ten reasons to avoid worshiping at the LTV altar:

  1. It’s a Tool, Not a Strategy.  Heavy LTV companies forget that the LTV model does not create sustainable competitive advantage. You shouldn’t’ confuse output with input. The LTV formula is a measurement tool to be used by marketing to test the effectiveness of their marketing spend – nothing more and nothing less. If one asserts that buying customers below what they charge them is a corporate strategy, this is in essence an arbitrage game, and arbitrage games rarely last. Too many of the variables (specifically ARPU and SAC) are outside of your control, and nothing would prevent another player from executing the exact same strategy. It’s not rocket science; it’s a formula that any business school graduate can calculate. Do not fool yourself into believing it creates a proprietary advantage.
  2. The LTV Model Is Used To Rationalize Marketing Spending.  Marketing executives like big budgets, as big budgets make it easier to grow the top line.  The LTV formula “relaxes” the need for near term profitability and “justifies” the ability to play it forward – to spend today for benefits that are postponed into the future. It is no coincidence that companies that put a heavy emphasis on LTV are also the ones that have massive losses as they scale, frequently even through an IPO. Consider that most companies limit any “affiliate fee” they would be willing to spend to 5-10% of sales. Yet when they are marketing, they use different math. They use LTV math, and all the sudden it’s acceptable to spend 30-50% of revenue on customer acquisition. Find the most boisterous executive recommending excessive spending, and you will usually find a loyal servant of the LTV religion.
  3. The Model is Confused and Misused. Frequently the same group that is arguing for more spending is the same one that “owns” the LTV calculation. (This is a mistake – finance should monitor LTV).  As a result, it is not uncommon for one to see shortcuts taken that allow for greater freedom. As an example, marketers often divide spend by total customers to calculate SAC rather than just those customers that were “purchased.” If you have organic customers, they shouldn’t be included in the spend calculus. They would have arrived regardless of spend. Also, many people discount “revenues” rather than marginal cash contribution. It is critical to bundle all future variable costs of supporting the customer in order to fairly estimate the future contribution. As an example of the sloppiness that exists around the formula, consider this blog post (http://blog.kissmetrics.com/how-to-calculate-lifetime-value/) from KISS metrics, a company whose aim is to “help you make smarter business decisions.” Not only do they include a version of the model that specifically ignores future costs, but also they recommend taking an average of three different results, two of which are clearly flawed. This voodoo-math has no place as part of a multi-million dollar marketing exercise.
  4. Business Isn’t Physics – The Formula Is Not Absolute. LTV zealots often hold an overly confident view of the predictive nature of the formula. It’s not “hard science” like say predicting gravity. It’s at best a “good guess” about how the future will unfold. Businesses are complex adaptive systems that cannot be modeled with certainty. The future LTV results are simply predictions based on many assumptions that may or may not hold. Yet the LTV practitioner often moves forward with a brazen naiveté, evocative of the first time stock buyer who just found out about the price/earnings ratio, or the newcomer to Vegas who has just been taught the basics of twenty-one. LTV models win arguments because executives perceive them to be grounded in science. Just because its math, doesn’t mean its good math.
  5. The LTV Variables “Tug” at One Another. This may be the single most important issue and it lies at the heart of why the LTV model eventually breaks down and fails to scale ad infinitum. Tren Griffin, a close friend that has worked for both Craig McCaw and Bill Gates refers to the five variables of the LTV formula as the five horsemen. What he envisions is that a rope connects them all, and they are all facing different directions. When one horse pulls one way, it makes it more difficult for the other horse to go his direction. Tren’s view is that the variables of the LTV formula are interdependent not independent, and are an overly simplified abstraction of reality. If you try to raise ARPU (price) you will naturally increase churn. If you try to grow faster by spending more on marketing, your SAC will rise (assuming a finite amount of opportunities to buy customers, which is true). Churn may rise also, as a more aggressive program will likely capture customers of a lower quality. As another example, if you beef up customer service to improve churn, you directly impact future costs, and therefore deteriorate the potential cash flow contribution. Ironically, many company presentations show all metrics improving as you head into the future. This is unlikely to play out in reality.
  6. Growing Becomes a Grind. Let’s say you have a company that estimates it will do $100mm in revenue this year, $200mm the next, and $400mm the year after that. In order to accomplish those goals it is going to invest heavily in marketing – say 50% of revenues. So the budget for the next three years is $50mm, $100mm, and $200mm. How realistic is it to assume that your SAC will drop as you 4X your spend? Supply and demand analysis suggests the exact opposite outcome. As you try to buy more and more of a limited good, the price will inherently increase. The number one place on the planet for marketing spend is Google Adwords, and make no mistake about it, this is an increasingly finite resource. Click-outs are not growing at a meaningful pace, and key word purchases are highly contested. Assuming you will “get better” at buying while trying to buy more is a daunting assumption. The game will likely get tougher not easier.
  7. Purchased Customers Underperform Organic on Almost Every Metric. Organic users typically have a higher NPV, a higher conversion rate, a lower churn, and more satisfied than customers acquired through marketing spend. LTV heavy companies are in denial about this point. In fact, many of them will argue until they are blue in the face that the customer dynamics are the same while this is rarely the case. A customer that “chooses” your firm’s services will be much more staisfied than one that is persuaded to buy your product through spend. Find any high-marketing spend consumer subscription company, and I will show you a company with numerous complaints at the Better Business Bureau. These are companies that make it almost impossible to terminate your subscription. When you are scheming on how to trap the customer from finding the exit you are not building a long-term brand.
  8. The Money Could Go to the Customer.Think about this. If you are a company that spends millions and millions of dollars on marketing, wouldn’t you be better off handing that money to the customer versus handing it to a third-party who has nothing to do with the future life-time value of the customer? Providing a better value-proposition to the customer is much more likely to endure goodwill than spending on marketing. A heavy marketing spend necessitates a higher margin (to cover the spend), and therefore a higher end user price to the customer! So the customer is negatively impacted by the presence or “need” of the marketing program. Plus, a margin umbrella now exists for competition that chooses to undercut your margin model with a more efficient customer acquisition strategy (such as giving the customer the money).“More and more money will go into making a great customer experience, and less will go into shouting about the service. Word of mouth is becoming more powerful. If you offer a great service, people find out.” – Jeff Bezos
  9. LTV Obsession Creates Blinders. Many companies that obsess over LTV, become overwhelmed by LTV. In essence, the formula becomes a blinder that restricts creativity and open-mindedness. Some of the most efficient forms of marketing are viral, social, and effective PR (public relations). Most companies that obsess about LTV are less skilled at these more leveraged techniques. Ironically, it’s the scrappy and capital starved startup with absolutely no marketing budget that typically finds a clever way to scale growth organically.  I love this historic slide from Skype comparing their SAC with that of Vonage, an iconic disciple of LTV analysis.
Image

10. Tomorrow Never Arrives.  The Utopian destination imagined by the LTV formula is a mirage. It almost never works out as planned in the long run. Either growth begins to slow, or you run out of capital to continue to fund losses, or Wall Street cries uncle and asks to see profitability. When this happens the frailty of the model begins to appear. SAC is a little higher than expected. You met your growth target, but the projected loss was bigger than expected. Wall Street is hounding you for churn numbers, but you are reluctant to give them out. The lack of transparency then leads to cynicism, and everyone assumes the worse. It turns out that the excessive marketing spend was also propping up repeat purchase, and pulling back to achieve profitability is increasing churn. Moreover, a negative PR cycle has ensued as a result of your stock decline, and the press’ new doubts about your model. This also impacts results, and customer perception of your brand. The bottom line is that “one day we can stop spending and be remarkably profitable” rarely comes to fruition.

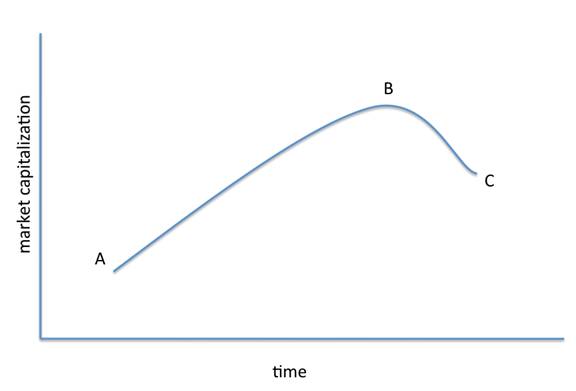
It is not impossible to create permanent equity value with the LTV approach, but it’s a dangerous game of timing – you don’t want to be the peak investor. Let’s say a new business starts with an early market capitalization of A (see graph below). Through aggressive marketing techniques, and aggressive fund raising, the company is able to achieve amazing revenue growth (and corresponding losses), but nonetheless creates a rather sizable organization. At this point, the company is value at point B. Eventually, however, gravity ensues and the constraints outlined herein raise their head, resulting in a collapse to point C.  For early founders and investors at point A, they may do OK (as long as C>A), but it will be accomplished on the backs of later stage investors that helped fund the unsustainable push to point B. This is the story of many a telecom and cable provider expansion history, as well as a few recent Internet companies.
Image

This should not be misconstrued as a eulogy for the LTV formula. It has a very important place in business as a way to contrast and compare alternative marketing programs and channels. It is a tactical marketing tool that requires candor and thoroughness in its implementation. The fundamental reason that it is so amazingly dangerous and seductive is its simplicity and certainty. Generic marketing is conceptual. LTV marketing is specific. Building a plan to grow to a million users organically is an order of magnitude more difficult than doing it with the aid of the LTV formula. There is comfort in its determinism, and it is simply easier to do.

Some people wield the LTV model as if they were Yoda with a light saber; “Look at this amazing weapon I know how to use!” Unfortunately, it is not that amazing, it’s not that unique to understand, and it is not a weapon, it’s a tool. Companies need a sustainable competitive advantage that is independent of their variable marketing campaigns. You can’t win a fight with a measuring tape.

I hope you are enjoying a stylish fall season!  I am so excited to share a few of my recent media appearances from the campaign trail and update you on fashion events in November. I hope you enjoy the fun tips and join me at one of the special events!

Stay in touch,
Lauren

__________________

Capitol File magazine shines the spotlight on Lauren and she reveals her style philosophy!

Lauren breaks down the evolution of political style and dressing for votes with Reuters!

Lauren dishes on Janna Ryan’s style on Entertainment Tonight!

The Insider asks Lauren to rank Ann Romney’s style!

CATCH LAUREN AROUND TOWN

  • Saturday, November 10th: Join Lauren at Lord & Taylor, Tysons Corner Center for an afternoon of fashion, style and beauty! Lauren will be hosting a one-of-a-kind runway show previewing gowns for the upcoming inaugural balls. Learn how to match the dress to your invite! Festivities begin at 2pm with mini-makeover stations, bellini’s and cupcakes! Event is complimentary and no RSVP is needed.
  • Wednesday, November 14th: An evening of style featuring a fashion presentation by Lauren to benefit the worldwide Fistula Fund at Weil Gotshal. Lauren will feature the latest winter trends and help you dress for the holiday season! The event will be held from 6:30-9pm at 1300 Eye Street NW, Suite 900, Washington, DC. Tickets, $35-$55; RSVP to attend, StyleRSVP@weil.com.
  • Saturday, November 17th: Join Lauren for the Fall Cosmetic Trend Show at Lord & Taylor, Tysons Corner Center. Learn about the latest trends in skincare and make-up from industry insiders and enjoy makeovers and mimosas! Event is complimentary, RSVP to Lauren@styleauteur.com for your goody bag!
  • Shopping Alert! Two of the best bargain shopping days are ahead: Black Friday (11/23) and Cyber Monday (11/26). Be sure to follow me on Twitter @Styleauteur and Facebook Styleauteur for the latest tips, tricks and trends to get the most bang for your buck!

FOLLOW LAUREN ON THE HUFFINGTON POST

Become a fan and subscribe to Lauren’s style column in The Huffington Post! The Fashion Whip examines the impact of fashion, style, and executive presence in politics.

Don’t forget to catch Lauren on Twitter and Facebook. And feel free to Forward this Newsletter to a Friend.

Sincerely,
~ The Styleauteur Team

Article from GigaOm.

Sandy isn’t just wreaking havoc for utilities and conventional power plant companies on the east coast. The hurricane is also delaying some solar power plant project work for First Solar, which on Thursday reduced its 2012 sales forecast and also boosted its earnings projection.

The Arizona-based company said the hurricane is also disrupting the supply of components for its solar products, which include panels and trackers that prop up the panels and tilt them to follow the sun’s movement throughout the day. For 2012, First Solar now expects to generate $3.5 billion to $3.8 billion in sales — previously it was looking at $3.6 billion to $3.9 billion. Non-GAAP earnings should hit $4.40 to $4.70 per share, however, instead of $4.20 to $4.70.

The company issued the forecast along with its third-quarter financial results, which saw its sales decline year-over-year sales to $839.1 million from $957.3 million. First Solar posted a net income of $1 per share for the third quarter, down from $2.25 per share in the same period a year ago, thanks to charges related to its restructuring efforts to reduce costs. But still, a profit in a difficult year.

“The solar market remains challenging, but we are continuing to gain traction in the new sustainable markets we’re targeting and expanding our global presence,” said Jim Hughes, First Solar’s CEO, during a conference call with analysts.

First Solar executives highlighted the progress they have made in opening up new markets. The company has vowed to build its business in places with minimal government subsidies, which so far have been responsible for the rise of the global solar market. Europe has been the largest market, but the pace of its growth will likely slow over time as governments gradually reduce their incentives.

During the third quarter, the company announced it was chosen to build a 13 MW power plant for the Dubai Electricity & Water Authority. First Solar inked deals to sell its cadmium-telluride solar panels for a 25 MW project in the state of Rajasthan in India and for two other projects totaling 50 MW in the same state. The company also signed a memorandum of understanding with a power plant operation and maintenance company in Indonesia to work on 100 MW of projects.

First Solar also hired Bruce Yung as its China manager during the third quarter. The company tried to crack the Chinese market before but hasn’t seen much success. Although China presents lots of opportunities, its government also is keen on boosting the domestic market for Chinese solar manufacturers.

In recent years, First Solar has been building its power plant development expertise and amassed an impressive pipeline of projects under development. That business is more lucrative – the company can make money from developing, building and operating solar power plants (for owners it sells the power plants to) that use its own solar panels. The company is building the largest solar power plant project in the U.S. – the 550MW Topaz Solar Farms in central California. The vast majority of the 3 GW of projects under development that it’s inked power sales agreement contracts for are in North America.  Now the company’s hope is to develop solar power plants in other parts of the world.

First Solar has no intention of conquering the rooftop segment – its panels are less expensive but also less efficient at converting sunlight into electricity as other major brands. That means an array with First Solar’s panels will take up more space than the one with more efficient solar panels. Hughes also told analysts that the rooftop market has less brand loyalty and cares less about how well the solar panels will perform over decades.

Photos of Topaz Solar Farms by Ucilia Wang.
Read more here.

CEO: Does Your Team Have Control of the Ball?

The team watching the ball slip away…

“The only players who survive in the pros are the ones able to manage all their responsibilities.” – Tom Brady, Quarterback of the New England Patriots

Football, rugby, or any other sport organized around a finely-tuned playbook, requires players to understand roles and execute plays in both familiar or unplanned situations. Each player has defined roles and responsibilities based on his skills; that player is fully aware of his role, the roles of others and has studied the plays. A solid playbook enables a cohesive team to maintain control of the ball and win.

Does your company’s playbook have:

This all too common, weak people/process combination creates lots of broken plays. Basic things like roles, skills, processes really should be a given in any organization.

But if that’s what’s ‘supposed to be’, then why have I regularly seen many corporate fumbles, pigpiles, tangled situations and outright conflict over ‘who does what and how’?

Thinking Horizontally

Many organizations are driven (dominated?) by a particular function such as engineering, sales, production, or in the case of professional service firms, project delivery. In my consulting and coaching work, I’ve worked with strong CEOs that are able to push the business forward by being grounded in one of these personal skill sets. This functional strength can be a real asset, and in many cases, it was the driving force that launched the company and enabled it to grow.

In initial group meetings with company teams, to break the ice I often ask a variation of the question: “Who runs the company, sales, manufacturing or engineering.” After I ask the question, I wait to hear the noise from the pin dropping…:)

As a company’s overall operations increase in complexity, great execution only happens if all the business functions work together seamlessly. However, some of the same CEOs that are grounded in one strong functional skill set don’t make needed changes to their process/operational playbook as the company evolves. The CEO may ignore or trivialize the importance of looking at the overall business ‘horizontally’.

The Line of Scrimmage

Most of the confusion I’ve experienced related to process playbooks has been in organizations that have a complex sales process that involves:

  • custom or semi-custom products
  • customer orders with product/service specifications that could change from order to order
  • contracts/proposals that have unique conditions
  • high customer expectations related to quality, testing, product acceptance

Examples of a some of types of organizations that fit these order profiles are:

  • specialty boxmakers
  • magazine printers
  • specialty window, door manufacturers
  • precision machining
  • chemical formulations
  • custom industrial equipment
  • IT consulting
  • various professional service firms
  • lots of others you could name

Piling On –> Breakdowns in Key Processes = Trouble

What happens when the process playbook doesn’t exist, is getting dusty on the shelf, or needs a complete overhaul?

Piling on happens when: a) sales doesn’t get the order specs correct…there are flaws in design, scope, terms; b) estimating creates an inaccurately costed order with incorrect pricing; c) engineering designs what sales specified but not what the customer ordered; d) manufacturing builds what engineering designed; e) the product fails customer tests; f) rework is needed; g) you get the idea…

What are some of the negative impacts on the business performance when a company doesn’t have a clear playbook or deviates from the process playbook? Here’s a sample:

Solutions: How to prevent pigpiles, fumbled balls, and losing the game

Fixing process problems like those noted above is not a complicated task. It’s actually pretty simple to implement the necesssary changes, but the basics often get lost in the the day-to-day shuffle.

1) Establish process flows for unique as well as routine projects and stick to them

Breaking down the process into well-defined pieces facilitates successful execution – once processes are clearly articulated, people need to study their playook, understand their particular functions and own them.

2) Based on the particular process, define clear roles and responsibilities

I do this. You do that. (Why does this have to be hard?)
People need to do their job and be accountable for performance.
“That which is owned by all is cared for by no one”. (Unknown)

3) Establish a clear communication system horizontally across the process chain and vertically through management so that glitches are caught early

For example, if a key person in the chain will be on vacation or is ill during production, who needs to step up and carry the ball?

4) Management, through training, repetition, and even incentives, needs to reinforce the use of the process playbook

In organizations that tend to operate in a seat-of-the-pants mode, this may be the most difficult problem to solve. This is particularly true if there are employees who have difficulty sticking to their own functions. Commit to a cultural change program.

For incentives, why not reward the excellent winning ways of using the playbook? When the team(s) deliver excellent products, on time, don’t forget to recognize it.

5) Revisit processes on a regular basis

What’s working? What needs tweaking? Do we have the resources we need to keep our customers satisfied? What about the team? Changes in personnel, especially when the products involve technical expertise, might invite revisions to the playbook.

Does your company have control of the ball? If not, are you ready to ‘think horizontally’ and get your playbook in order?

Illustration by Drew Litton

Article from NYTimes.

Apple fired the executives in charge of the company’s mobile software efforts and retail stores, in a management shake-up aimed at making the company’s divisions work more harmoniously together.

The biggest of the changes involved the departure of Scott Forstall, an Apple veteran who for several years ran software development for Apple’s iPad and iPhone products. Mr. Forstall was an important executive at the company and the one who, in many respects, seemed to most closely embody the technology vision of Steven P. Jobs, the former chief executive of Apple who died a year ago.

But Mr. Forstall was also known as ambitious and divisive, qualities that generated more friction within Apple after the death of Mr. Jobs, who had kept the dueling egos of his senior executives largely in check. Mr. Forstall’s responsibilities will be divided among a few other Apple executives.

While tensions between Mr. Forstall and other executives had been mounting for some time, a recent incident appeared to play a major role in his dismissal. After an outcry among iPhone customers about bugs in the company’s new mobile maps service, Mr. Forstall refused to sign a public apology over the matter, dismissing the problems as exaggerated, according to people with knowledge of the situation who declined to be named discussing confidential matters.

Instead, Timothy D. Cook, Apple’s chief executive, in September signed the apology letter to Apple customers over maps.

Apple said in a news release on Monday that the management changes would “encourage even more collaboration” at the company. But people briefed on Apple’s moves, who declined to be identified talking about confidential decisions at the company, said Mr. Forstall and John Browett were fired.

Steve Dowling, an Apple spokesman, said neither executive was available for an interview. Mr. Forstall did not respond to interview requests over e-mail and Facebook.

Mr. Browett, who took over as head of the company’s retail operations in April, will also leave the company after a number of missteps. Apple said that a search for a new head of retail was under way and that the retail team would report directly to Mr. Cook in the meantime.

Mr. Forstall will leave Apple next year and serve as an adviser to Mr. Cook until then.

Eddy Cue, who oversees Apple’s Internet services, will take over development of Apple maps and Siri, the voice-activated virtual assistant in the iPhone. Both technologies have been widely criticized by some who say they fall short of the usual polish of Apple products.

Jonathan Ive, the influential head of industrial design at Apple, will take on more software responsibilities at the company by providing more “leadership and direction for Human Interface,” Apple said. Craig Federighi, who was previously in charge of Apple’s Mac software development, will also lead development of iOS, the software for iPads and iPhones.

Apple said Bob Mansfield, an executive who previously ran hardware engineering and was planning to retire from Apple, will lead a new group, Technologies. That group will combine Apple’s wireless and semiconductor teams. Apple in a statement said the semiconductor teams had “ambitious plans for the future.”

Recently, Mr. Mansfield had been working on his own projects at the company, operating without anyone reporting to him directly. One of the areas of interest Mr. Mansfield had been exploring is health-related accessories and applications for Apple’s mobile products, said an Apple partner who declined to be named discussing unannounced products.

Mr. Forstall was a staunch believer in a type of user interface, skeuomorphic design, which tries to imitate artifacts and textures in real life. Most of Apple’s built-in applications for iOS use skeuomorphic design, including imitating thread of a leather binder in the Game Center application and a wooden bookshelf feel in the newsstand application.

Mr. Jobs was also a proponent of skeuomorphic design; he had a leather texture added to apps that mimicked the seats on his private jet. Yet most other executives, specifically Mr. Ive, have always believed that these artifacts looked outdated and that user interface design on the computer had reached a point where skeuomorph was no longer necessary.

Mr. Forstall, who trained as an actor at a young age, also shared with Mr. Jobs a commanding stage presence at events introducing Apple products, often delivering his speeches with a pensive style that echoed that of Mr. Jobs.

According to two people who have worked with Apple to develop new third-party products for the iPhone, the relationship between Mr. Forstall and Mr. Ive had soured to a point that the two executives would not sit in the same meeting room together.

A senior Apple employee who asked not to be named said Mr. Forstall had also incurred the ire of other executives after inserting himself into product development that went beyond his role at the company. One person in touch with Apple executives said the mood of people at the company was largely positive about Mr. Forstall’s departure.

“This was better than the Giants winning the World Series,” he said. “People are really excited.”

The departure of Mr. Browett was less surprising to outsiders. In August, the company took the unusual step of publicly apologizing for a plan by Mr. Browett to cut back on staffing at its stores. Charlie Wolf, an analyst at Needham & Company, said he was never convinced that Mr. Browett was a good choice to join Apple because he had previously run Dixons, a British retailer that is viewed as being more downmarket than Apple’s retail operations.