Feeds:
Posts
Comments

gp_nl_header
The Advantages of a “Date-Certain” Mergers and Acquisition Process Over a “Standard Mergers and Acquisitions Process”
Every venture capital investor hopes that all of his investments will succeed. The reality is that a large percentage of all venture investments must be shut down. In extreme cases, such a shut down will take the form of a formal bankruptcy or an assignment for the benefit of creditors. In most cases, however, the investment falls into the category of “living dead”, i.e. companies that are not complete failures but that are not self-sustaining and whose prospects do not justify continued investment. Almost never do investors shut down such a “living dead” company quickly.

Most hope against hope that things will change. Once reality sets in, most investors hire an investment banker to sell such a company through a standard mergers and acquisition process – seldom with good results. Often, such a process requires some four to six months, burns up all the remaining cash in the company and leads to a formal bankruptcy or assignment for the benefit of creditors. In many instances, there are a complete lack of bidders, despite the existence of real value in the company being sold.

The first reason for this sad result is a fundamental misunderstanding of buyer psychology. In general, buyers act quickly and pay the highest price only when forced to by competitive pressure. The highest probability buyers are those who are already familiar with the company being sold, i.e. competitors, existing investors, customers and vendors. Such buyers either already know of the company’s weakness or quickly understand it as soon as they see the seller¥s financials. Once the sales process starts, the seller is very much a wasting asset both financially and organizationally. Potential buyers quickly divide the company’s burn rate into its existing cash balance to see how much time it has left. Employees, customers and vendors grow nervous and begin to disengage. Unless compelled to act, potential buyers simply draw out the process and either submit a low-ball offer when the company is out of cash or try to pick up key employees and customers at no cost when the company shuts down.

The second reason for this sad result is a misunderstanding of the psychology and methods of investment bankers. Most investment bankers do best at selling “hot” companies, i.e. where the company’s value is perceived by buyers to be increasing quickly over time and where there are multiple bidders. They tend to be most motivated and work hardest in such situations because the transaction sizes (i.e. commissions) tend to be large, because the publicity brings in more assignments and because such situations are more simply more fun. They also tend to be most effective in maximizing value in such situations, as they are good at using time to their advantage, pitting multiple buyers against each other and setting very high expectations. In a situation where “time is not your friend”, the actions of a standard investment banker frequently make a bad situation far worse. First, since transaction sizes tend to be much smaller, an investment banker will assign his “B” team to the deal and will only have such team spend enough time on the deal to see if it can be closed easily. Second, playing out the process works against the seller. Third, trying to pit multiple buyers against each other and setting unrealistically high valuation expectations tends to drive away potential buyers, who often know far more about the real situation of the seller than does the investment banker.

“Date Certain” M&A Process” -The solution in a situation where “time is not your friend” is a “date-certain” mergers and acquisitions process. With a date-certain M&A process, the company’s board of directors hires a crisis management/ private investment banking firm (“advisor”) to wind down business operations in an orderly fashion and maximize value of the IP and tangible assets. The advisor works with the board and corporate management to:

1. Focus on the control, preservation and forecasting of CASH.
2. Develop a strategy/action plan and presentation to maximize value of the assets. Including drafting sales materials, preparing information Ïdue diligence war-room, assembling a list of all possible interested buyers for the IP and assets of the company and identifying and retaining key employees on a go-forward basis.
3. Stabilize and provide leadership, motivation and morale to all employees.
4. Communicate with the Board of Directors, senior management, senior lender, creditors, vendors and all stakeholders in interest.
The company’s attorney prepares very simple “as is, where is” asset-sale documents. (“as is, where is- no reps or warranties” agreements is very important as the board of directors, officers and investors typically do not want any additional exposure on the deal). The advisor then contacts and follows-up systematically with all potentially interested parties (to include customers, competitors, strategic partners, vendors and a proprietary distribution list of equity investors) and coordinates their interactions with company personnel, including arranging on-site visits. Typical terms for a date certain M&A asset sale include no representations and warranties, a sales date typically two to four weeks from the point that sale materials are ready for distribution (based on available CASH), a significant cash deposit in the $200,000 range to bid and a strong preference for cash consideration and the ability to close the deal in 7 business days.

Date certain M&A terms can be varied to suit needs unique to a given situation or corporation. For example, the board of directors may choose not to accept any bid or to allow parties to re-bid if there are multiple competitive bids and/or to accept an early bid. The typical workflow timeline, from hiring an advisor to transaction close and receipt of consideration is four to six weeks, although such timing may be extended if circumstances warrant. Once the consideration is received, the restructuring/insolvency attorney then distributes the consideration to creditors and shareholders (if there is sufficient consideration to satisfy creditors) and takes all necessary steps to wind down the remaining corporate shell, typically with the CFO, including issuing W-2 and 1099 forms, filing final tax returns, shutting down a 401K program and dissolving the corporation etc.

The advantages of this approach include the following:

Speed – The entire process for a date certain M&A process can be concluded in 4 to 6 weeks. Creditors and investors receive their money quickly. The negative public relations impact on investors and board members of a drawn-out process is eliminated. If circumstances require, this timeline can be reduced to as little as two weeks, although a highly abbreviated response time will often impact the final value received during the asset auction.

Reduced Cash Requirements – Given the date certain M&A process compressed turnaround time, there is a significantly reduced requirement for investors to provide cash to support the company during such a process.

Value Maximized – A company in wind-down mode is a rapidly depreciating asset, with management, technical team, customer and creditor relations increasingly strained by fear, uncertainty and doubt. A quick process minimizes this strain and preserves enterprise value. In addition, the fact that an auction will occur on a specified date usually brings all truly interested and qualified parties to the table and quickly flushes out the tire-kickers. In our experience, this process tends to maximize the final value received.

Cost – Advisor fees consist of a retainer plus 10% or an agreed percentage of the sale proceeds. Legal fees are also minimized by the extremely simple deal terms. Fees, therefore, do not consume the entire value received for corporate assets.

Control – At all times, the board of directors retains complete control over the process. For example, the board of directors can modify the auction terms or even discontinue the auction at any point, thus preserving all options for as long as possible.

Public Relations – As the sale process is private, there is no public disclosure. Once closed, the transaction can be portrayed as a sale of the company with all sales terms kept confidential. Thus, for investors, the company can be listed in their portfolio as sold, not as having gone out of business.

Clean Exit – Once the auction is closed and the consideration is received and distributed, the advisor takes all remaining steps to effect an orderly shut-down of the remaining corporate entity. To this end the insolvency counsel then takes the lead on all orderly shutdown items.

Gerbsman Partners focuses on maximizing enterprise value for stakeholders and shareholders in under-performing, under-capitalized and under-valued companies and their Intellectual Property. Since 2001, Gerbsman Partners has been involved in maximizing value for 76 Technology, Medical Device, Solar and Life Science companies and their Intellectual Property and has restructured/terminated over $810 million of real estate executory contracts and equipment lease/sub-debt obligations. Since inception, Gerbsman Partners has been involved in over $2.3 billion of financings, restructurings and M&A transactions.

Gerbsman Partners has offices and strategic alliances in Boston, New York, Washington, DC, McLean, VA, San Francisco, Europe and Israel.

Unknown
Email: Steve@GerbsmanPartners.com
Web: www.gerbsmanpartners.com
BLOG: http://blog.gerbsmanpartners.com

Jun 26, 2013

Whoever’s behind ‘My Startup has 30 Days to Live’ is hitting a chord

Senior Technology Reporter- Silicon Valley Business Journal

A Tumblr author claiming to be a startup entrepreneur is hooking techies, investors and the press with his My Startup Has 30 Days to Live blog.

Whether the anonymous author is telling a true tale, or whether he’s uncovered as the 2013 version of 2006 YouTube hoaxer “lonelygirl15,” his sad story of dashed entrepreneurial dreams is gripping Silicon Valley.

The writing has a ring of truth. The author claims to have been on the hamster wheel for about two years, getting into a top accelerator. He “hit the top of TechCrunch” and became viewed as a “rising star in the technology world,” the blog claims.

After compromising some vision for funding, the author claims to have gotten traction — but it didn’t keep the funders happy.

“I found myself sitting at my desk, afraid, alone and overwhelmed,” the blog says.

The first day’s blog ends with the author realizing he or she can’t make payroll and needing to fire the company’s first employee before he leaves on a planned vacation.

The second post, which went up today, is headlined “We’re killing it bro.”

“One of the first things you learn as an entrepreneur is that on some level, you’re only as good as your pitch,” it starts out. “The accelerators reinforce this by teaching you the art of storytelling, a skill that helps an investor sign a term sheet as much as it helps the father of a young child decide to take a pay cut to be part of something that’s amazing.”

This one could be the work of a writer hoping for a TV, movie or book deal. There is a lot of entertainment industry industry focus on Silicon Valley, evidenced by Mike Judge’s new HBO show and Bravo’s “Startups: Silicon Valley.”

Eventually, we will likely find out who is behind “My Startup Has 30 Days to Live” and will truly be able to evaluate its worth.

But for now, it has our attention.

Click here to subscribe to TechFlash Silicon Valley, the free daily email newsletter about the region’s founders and funders.

Cromwell Schubarth is the Senior Technology Reporter at the Business Journal.

Tech More: Mobile BI Intelligence Mobile Ads Mobile Advertising
Why Local-Mobile Marketing Is Exploding

Josh Luger      –         BI Intelligence

Location-based mobile marketing promises the sky: high conversion rates, surgical targeting, and rich consumer profiles.
But does it deliver? According to many accounts, it does.

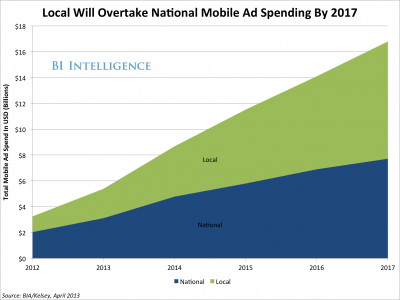
localvnatl-1

Not surprisingly, retailers, brands, and agencies are scrambling to hone their location-based approaches. These encompass everything from “geo-aware” and “geo-fenced” ad campaigns, to hyper-local efforts keyed to Wi-Fi hotspots, and algorithmic location-based targeting of audience segments like soccer moms, bargain hunters, coffee enthusiasts, etc.

In a new report from BI Intelligence on location-mobile marketing, we take a look at key stats on the location-based services marketplace that indicate it’s supremacy in mobile marketing, explain how the most important techniques (such as geo-aware, geo-fenced, audience-based local-mobile campaigns) work, examine the cornerstones – such as data and audience building – to a successful location-based mobile strategy, look at who has the valuable location-based data, and analyze the six most effective local-mobile marketing tactics.

Here’s an overview of the location-mobile marketing explosion:

Location is the new cookie: Collecting data has always been difficult because mobile does not support third-party cookies that travel easily across the ecosystem, allowing for straightforward tracking and data-gathering. That’s where location-based mobile technology comes in. It gives marketers new ways to identify and track mobile audiences, and with the aid of algorithms, it can also group them into behavioral and demographic segments for targeting.
Money is flowing into location-based mobile marketing: A recent survey of 400 brand executives by Balihoo found that 91% planned to increase their investments in location-based marketing campaigns in 2013. Finally, a study by Berg Insight found that location-enabled ad spend reached about 8% of total mobile ad spend for 2012. This proportion is expected to increase to 33% by 2017.
Location-based data is driving much of the interest – and success: Enabling campaigns with local data produces measurable results. In a study of over 2,500 of its mobile marketing campaigns, Verve found that its location-based ad efforts were about twice as effective as the mobile industry average click-through rate (CTR) of 0.4%. Geo-aware ads, geo-fenced ads, and location data paired with audience demographics or purchase intent are all proving to be extremely successful.
Location is extending beyond the smartphone: The location conversation may have started out as a way to take advantage of mobile phones, but as technology continues to evolve, the conversation needs to broaden. In 2012, only 12% of smartphone owners and 17% of tablet owners said they used their device throughout the entire shopping process. This year, one-third of smartphone and tablet owners said they did so. Additionally, more tablet consumers are beginning their shopping process on their tablets. This shows that location ads should be targeted to tablets as well as smartphones, because the first search for a local business might take place on a tablet.
In full, the report:

Takes a look at key stats on the location-based services marketplace that indicate it’s supremacy in mobile marketing;
Explains how the most important techniques, such as geo-aware, geo-fenced, audience-based local-mobile campaigns, work;
Examines the cornerstones – such as data and audience building – to a successful location-based mobile strategy;
Looks at who has the valuable location-based data;
Analyzes the six most effective local-mobile marketing tactics.

Read more: http://www.businessinsider.com/local-mobile-marketing-exploding-2013-6#ixzz2XHehbbNw

stlogo

We are excited to share that Lauren A. Rothman is featured on Oprah.com! Early buzz for Style Bible: What to Wear to Work (Bibliomotion October 2013)

59

To schedule an interview with On-Air Style Expert & Author
Lauren A. Rothman, please contact:
Phone: +1.202.631.8878
Email: lauren@styleauteur.com
Web: www.styleauteur.com
Twitter: twitter.com/styleauteur
Facebook: facebook.com/styleauteur
TV Clips: http://styleauteur.com/category/video-2/
___________________________________________________________________

6012 Fashion Mistakes That Make You Look Older
By Pamela Masin

You Took the Song “Paint It, Black” Literally
Black does wonders for trimming a figure and is appropriate for almost every occasion, but as women get older, their skin tends to become paler-and wearing black can create a harsh contrast that emphasizes wrinkles and calls attention to dark shadows under the chin and around the eyes. Add a bright accessory like a scarf or a statement necklace-any pop of color will lessen the washed-out effect, says Lauren Rothman, the founder of Styleauteur.com and author of Style Bible: What to Wear to Work. She also suggests shopping for earthy neutrals-like cocoa, olive, camel or gray-which are subdued but still add contrast. Also, jewel tones are a color group that flatters most women. Here’s a way to find which works best with your skin tone.

Your Skirt Length Is Moving Down, Down, Down


Just because your age is increasing doesn’t mean your hemline has to as well. A skirt that grazes close to your ankles may hide slightly saggy knees, but it also tends to make women look wider and frumpier. Rothman says to find the most flattering skirt length for your shape, look in the mirror and note the slimmest part of the area around your knee-right above, right below or in the middle-and that’s where your hemline should hit. If you want more coverage, try a form-fitting midiskirt, which comes to the middle of your calf. This is a tricky length, so use our guide to finding the right midi hemline for your height.

Your Jeans Have Too Much Stretch


Stretch denim is a gift to women who shop for both comfort and style, but erring on the side of too much comfort can lead to lumpiness. “It’s best to look for jeans with 2 percent elastic fiber,” says Rothman. On the care label, you’ll see Lycra, spandex or elastane. The right jeans will follow your silhouette, have enough stretch so that your legs won’t look as if they’re fighting to break free from your pants and, unlike denim with 4 percent or more elastic fiber, won’t sag at the tush.

You’re Hiding Your Neck


It seems like the easy fix: Cover as much of the neck as possible with a turtleneck, but a better choice is a V-neck or scoop neck, which draws the eye to your décolletage (so long as it doesn’t show cleavage). Collared shirts draw attention away from the neck area while giving a little more coverage. You might also choose a statement necklace that sits a little longer. “Avoid chokers,” says Rothman. Pick a style that’s at least 22 inches long.

You’re Heaviest Below the Knees


Chunky heels and platform shoes add unnecessary heaviness to the bottom portion of your body. “Look for something more sleek and slim,” says Rothman. Stilettos are Rothman’s choice, though she suggests kitten heels for the more walking-inclined among us. Either way, she says, you can’t go wrong with a pointed toe.

Read more:  http://www.oprah.com/style/Fashion-Tips-To-Look-Younger-Style-Mistakes-That-Age-You/1#ixzz2Ws3gsT7n

Follow @Styleauteur  on Twitter & ‘Like’ Styleauteur on Facebook

gp_nl_header

Bidding Process – Procedures for the Sale of certain Assets and Intellectual Property of Portaero, Inc.

Further to Gerbsman Partners e-mail of June 11, 2013 regarding the sale of certain assets of Portaero, Inc., I attach the draft legal documents that we will be requesting of bidders for certain Assets and Intellectual Property of Portaero, Inc.  All parties bidding on the assets are encouraged, to the greatest extent possible, to conform the terms of their bids to the terms and form of the attached agreement.  Any and all of the assets of Portaero, Inc. will be sold on an “as is, where is” basis and will be subject to “The Bidding Process for Interested Buyers”, outlined below.

I would also encourage all interested parties to have their counsel speak with David Garcia, Esq. and/or Holly Olson, Esq., counsel to Portaero, Inc.

For additional information please contact David Garcia, Esq, 775 327 3021  dgarcia@hollandhart.com and/or Holly Olson, Esq, hbolson@hollandhart.com

Please review in detail, the “Bidding Process for Interested Buyers” below.

The key dates and terms include:

The Bidding Process for Interested Buyers
Interested and qualified parties will be expected to sign a Confidential Disclosure Agreement (attached hereto as Appendix A) to have access to key members of management and intellectual capital teams and the due diligence “war room” documentation (“Due Diligence Access”). Each interested party, as a consequence of the Due Diligence Access granted to it, shall be deemed to acknowledge and represent (i) that it is bound by the bidding procedures described herein; (ii) that it has had an opportunity to inspect and examine the Portaero, Inc. assets and to review all pertinent documents and information with respect thereto; (iii) that it is not relying upon any written or oral statements, representations, or warranties of Gerbsman Partners, or their respective staff, agents, or attorneys; and (iv) all such documents and reports have been provided solely for the convenience of the interested party, and Gerbsman Partners (and their respective staff, agents, or attorneys) do not make any representations as to the accuracy or completeness of the same.

Following an initial round of due diligence, interested parties will be invited to participate with a sealed bid, for the acquisition of the Portaero, Inc. assets. Each sealed bid must be submitted so that it is received by Gerbsman Partners no later than Tuesday, July 16, 2013 at 3:00pm Pacific Daylight Time (the “Bid Deadline”) at Portaero, Inc.’s office, located at 21631 Stevens Creek Blvd., Cupertino, CA 95014.  Please also email steve@gerbsmanpartners.com with any bid.

Any person or other entity making a bid must be prepared to provide independent confirmation that they possess the financial resources to complete the purchase.  All bids must be accompanied by a refundable deposit in the amount of $100,000 (payable to Portaero, Inc.).  The deposit should be wired to Portaero, Inc.’s attorneys (information will be provided).  The winning bidder will be notified within 3 business days of the Bid Deadline. The deposit will be held in trust by Portaero’s counsel.  Unsuccessful bidders will have their deposit returned to them within 3 business days of notification that they are an unsuccessful bidder.

Portaero, Inc. reserves the right to, in its sole discretion, accept or reject any bid, or withdraw any or all assets from sale.  Interested parties should understand that it is expected that the highest and best bid submitted will be chosen as the winning bidder and bidders may not have the opportunity to improve their bids after submission.

Portaero Inc. will require the successful bidder to close within a 7 day period. Any or all of the assets of Portaero, Inc. will be sold on an “as is, where is” basis, with no representation or warranties whatsoever.

All sales, transfer, and recording taxes, stamp taxes, or similar taxes, if any, relating to the sale of the Portaero, Inc. assets shall be the sole responsibility of the successful bidder and shall be paid to Portaero, Inc. at the closing of each transaction.